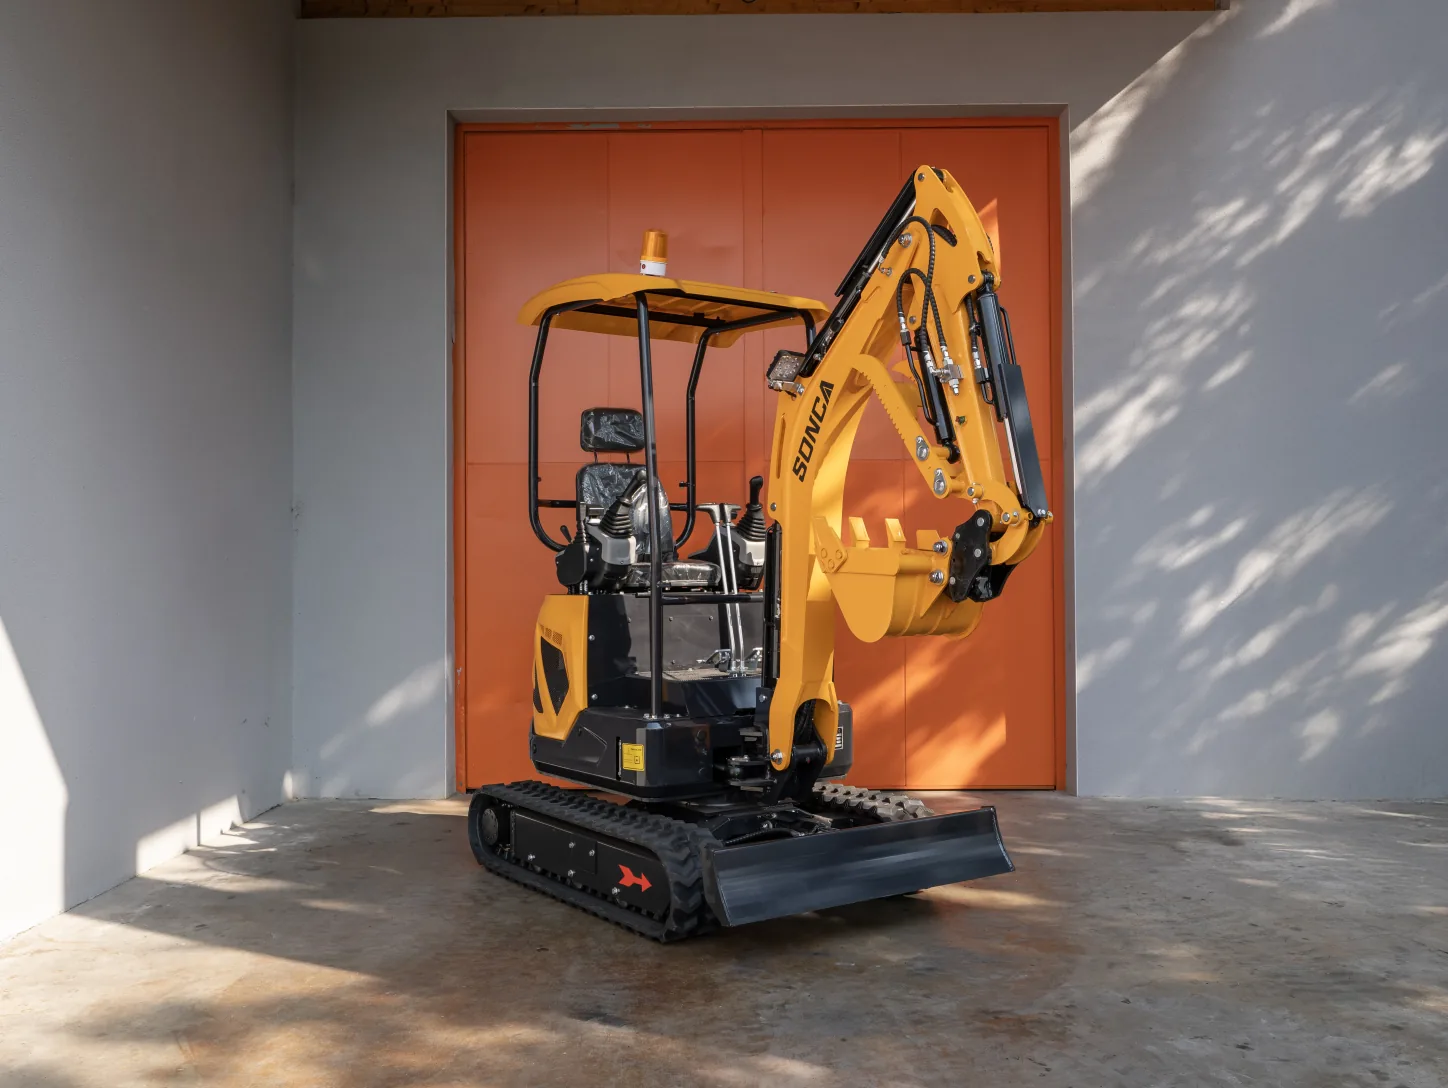
Acquiring a mini excavator represents a reasonable investment compared with larger machines: at CZN Machinery, new models start from €4,125 excl. VAT. That said, preserving your cash flow remains a major concern, whether you are a landscaping craftsman, a farmer, a civil engineering company or a private builder. Mini excavator financing lets you spread the outlay over time while starting to generate value as soon as the machine is delivered.
Three main families of solutions exist: the conventional loan, lease-purchase (LOA) and the business finance lease (leasing). Each one answers a different budgetary and tax logic. This guide details their mechanisms, their costs and their advantages to help you decide with full knowledge of the facts.
Why finance rather than buy outright?
Paying outright remains possible and avoids any financing cost. But for a professional, tying up several thousand euros in one go is not always the best management decision. Financing offers several advantages:
- Preserving cash flow for unforeseen expenses, wages or other investments.
- Putting the machine to work from the moment it enters service: the mini excavator generates turnover while it is being repaid.
- Spreading the expense over a period consistent with how long you will use the machine (often 36 to 60 months).
- Optimising taxation thanks to the deductibility of interest or rentals.
Before deciding, it can be helpful to compare buying and renting: our guide should you buy or rent a mini excavator? sets out the basis of the reasoning according to how often you use it.
The conventional amortising loan
The conventional loan (or dedicated loan) is the best-known formula. You borrow a sum to finance the purchase of the mini excavator, then repay it through monthly instalments comprising capital and interest. From the outset, you own the machine: it appears on the asset side of your balance sheet if you are a professional, or simply in your personal estate if you are a private individual.
The strengths
- Immediate ownership: no purchase option to exercise at the end of the contract.
- Simplicity: once the loan is settled, the machine belongs entirely to you and its resale value is yours.
- Accessible to private individuals as well as professionals.
The limits
- A deposit is often required.
- For a professional, only the interest is deductible (not the capital), but the machine can be depreciated for accounting purposes.
This formula suits buyers who intend to keep their mini excavator for several years and make the most of its later resale.
Lease-purchase (LOA)
Lease-purchase, also known as leasing with a purchase option, involves renting the mini excavator for a set period (for example 36 or 48 months) in exchange for rentals. At the end of the term, you can exercise the purchase option for a residual value fixed at signing and become the owner, return the machine or, in some cases, start a new contract.
The strengths
- Rentals that are often more flexible than a loan instalment, sometimes with an adjustable higher first rental.
- Flexibility at the end of the contract: buy, return or change machine.
- The residual value, known in advance, makes budget planning easier.
The limits
- You only become the owner after exercising the purchase option.
- The total cost may exceed that of a conventional loan if the option is exercised.
Lease-purchase appeals to buyers who want to remain free to renew their equipment or who are still unsure of the ideal machine. If that is your case, the guide how to choose your mini excavator will help you target the right model before committing.
Need a financing solution?
CZN Machinery offers financing via Sofinco, with a personalised assessment of your application.
Business leasing / finance lease
The finance lease (leasing in the strict sense) is reserved for professionals. A finance company buys the mini excavator and rents it to you over a defined period. You pay rentals that are fully deductible from taxable income, and a purchase option for a generally low residual value is provided at the end of the contract.
The strengths
- Rentals deductible as expenses: the entire rental reduces taxable profit (under the conditions set by the regulations).
- No asset on the balance sheet during the lease: the machine only appears on the balance sheet when the option is exercised.
- 100% financing possible, often without a significant deposit.
- Preservation of your bank credit lines for other needs.
The limits
- Reserved for professional structures (craftsmen, companies, farmers).
- A firm commitment for the duration of the contract, with penalties in the event of early termination.
The finance lease is particularly valued by very small businesses and farms that want to optimise their taxation while equipping their fleet. For agricultural use, see our dedicated guide on the mini excavator in agriculture.
Tax benefits worth knowing
Taxation depends on your status (private individual or professional) and the financing method chosen. Here are the main principles, to be confirmed with your accountant:
- VAT recovery: a VAT-registered professional can generally recover the VAT on the purchase or on the rentals of a mini excavator used for their activity.
- Depreciation: in the case of a purchase (outright or on credit), the machine is depreciated for accounting purposes over its useful life, which reduces taxable profit year after year.
- Deductibility of rentals: with a finance lease and a professional lease-purchase, the rentals are recorded as deductible expenses.
- Deductibility of interest: with a conventional loan, only the loan interest (not the capital) is deductible, in addition to depreciation.
The right tax choice therefore depends on your profit, your tax regime and your usage horizon. A machine you intend to keep for a long time often argues for buying; a need for flexibility and short-term optimisation points towards leasing. To frame your overall budget, also consider reading our guide on the price of a mini excavator.
Comparison of the three solutions
The table below summarises the main differences between the three ways of financing a mini excavator.
| Criterion | Conventional loan | LOA | Finance lease (leasing) |
|---|---|---|---|
| Audience | Private individuals and professionals | Private individuals and professionals | Professionals only |
| Ownership of the machine | Immediate | On exercising the option | On exercising the option |
| Deposit | Often required | Higher first rental possible | Often low or none |
| Tax deduction | Interest + depreciation | Rentals (if professional) | Deductible rentals |
| End-of-contract flexibility | Low (already the owner) | High | Medium |
| Accounting balance sheet | Fixed asset | Off balance sheet until the option | Off balance sheet until the option |
No solution is universally better: it all depends on your status, your taxation and how often the machine is used. If you only have a one-off job to carry out, simply renting a mini excavator may even prove more economical than financing a purchase.
Financing your mini excavator with CZN
A direct importer based in Toulouse since 2019, CZN Machinery offers a financing solution via Sofinco to support your acquisition. This lets you spread your investment without tying up all your cash flow, and benefit from a single point of contact for both the machine and the credit.
Our strengths for securing your project:
- Competitive prices thanks to direct importing, with new mini excavators from €4,125 excl. VAT.
- 2-year warranty (24 months) on new machines, and aftersales handled in France.
- Delivery throughout France and a showroom in Toulouse to view the machines.
- A fleet of used machines inspected across 50 points and guaranteed for 6 months, which can also be financed.
- More than 5,500 customers already assisted.
Whether you are after a compact micro excavator for trenches or a more powerful model for earthworks, you will find the right machine in our range of mini excavators. Our team can study with you the financing method most consistent with your activity and your taxation.
Planning to buy a mini excavator?
Let's talk about your financing and the model that matches your needs.
In summary, the choice between a loan, lease-purchase and leasing depends above all on your status and your strategy. The conventional loan suits those who want immediate ownership, lease-purchase offers flexibility, and the finance lease optimises taxation for professionals. In all cases, take the time to compare the total cost and have the tax aspect confirmed by your accountant before signing.